

Terms such as “later life lending” and “equity release” risk creating barriers between borrowers and the mortgage solutions they need, industry figures have warned.
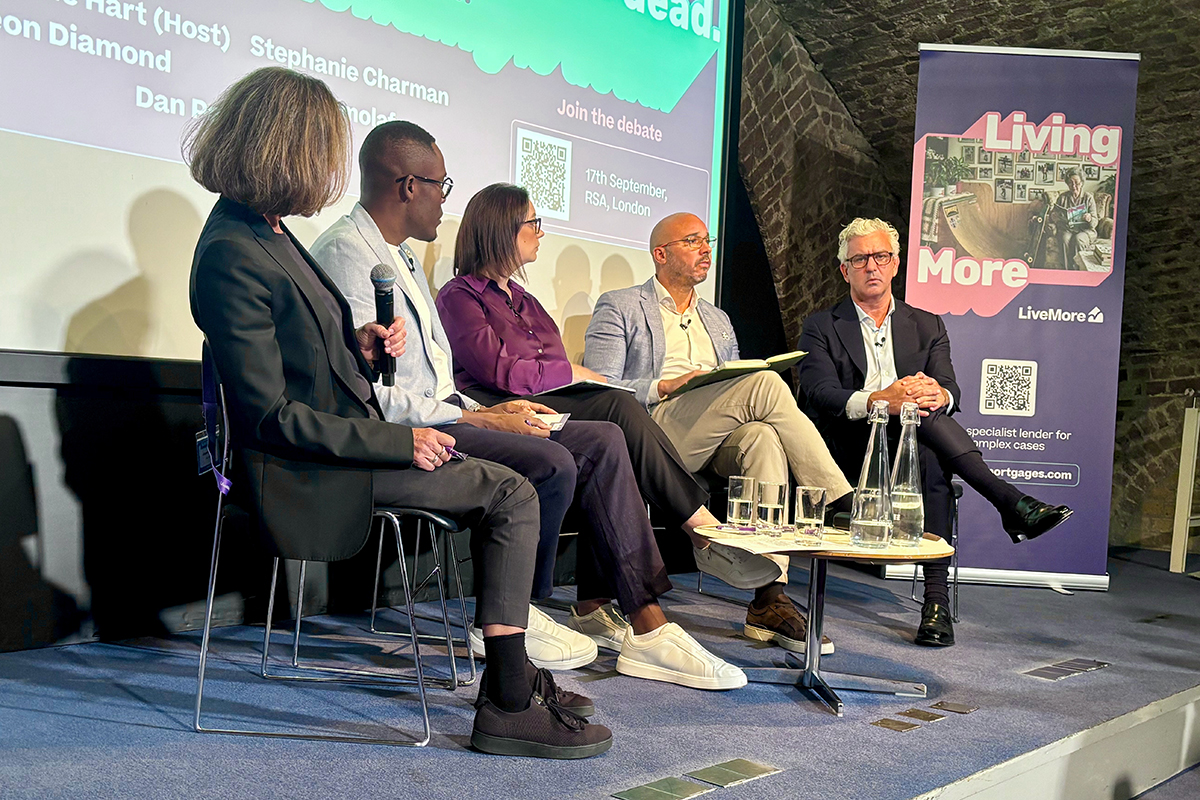
A panel debate hosted by LiveMore at the Royal Society of Arts on 17 September questioned whether the mortgage industry’s traditional product categories remain appropriate as borrowers increasingly work, borrow and make major financial decisions later in life.
The discussion brought together Leon Diamond, founder and chief executive of LiveMore, Stephanie Charman, chief executive of the Association of Mortgage Intermediaries, Dan Payne, chief operating officer at L&C, and former financial adviser and financial educator Peter Komolafe.
Diamond, who had framed the event around the deliberately provocative proposition that “later life lending is dead”, argued that describing borrowers aged 50 or 55 as being in “later life” was increasingly at odds with the way people actually live.
He said: “People are working longer and no longer have one job pay off their house, just staying in their house. Life is complex; It’s no longer about just going into retirement at 60 or 65.”
TERMINOLOGY CAN CREATE A BARRIER
The debate also questioned whether replacing “later life lending” with another label, such as “life-stage lending”, would solve the underlying problem.
Payne said the language used by the industry could directly affect how consumers regarded both themselves and the products available to them.
He said: “I think it is industry centric, isn’t it? The language we use in the market actually shapes customer perception, and if somebody was to say to me, ‘you’re suitable for later life’, I’ve probably been insulted. I’m shocked, I feel slightly vulnerable or uncomfortable.”
He added: “I want to raise some money to help my daughter on the property ladder. I don’t wake up and think I need later life lending. I’d probably wake up thinking I need finance.
“So I think that the problem is with terminology we use, we have to change that language, as it also creates a barrier.”
Komolafe said product names could also shape how consumers interpreted their own eligibility before they have spoken to an adviser.
He said: “I often find is that the title of the product puts people off, because ultimately, it doesn’t necessarily resonate with where they are or what they think they need.
“We do need to be aware that the name of the product directly impacts perception and how people frame it in their mind in terms of where it fits it to their own structure and their own life.”
CUSTOMERS LOOK FOR SOLUTIONS
Charman said the industry’s focus should be less on presenting products to customers and more on identifying the financial problem they are trying to solve.
She said: “The customer’s not looking for a product, are they? They’re looking for a solution.
“They’re a first-time buyer they just want to buy a home.”
The issue was particularly acute around equity release. Diamond argued that terminology and distribution structures could steer both consumers and advisers towards one part of the market before all of the available options have been considered.
He said a consumer searching online for a mortgage at age 60 could typically be directed towards an equity release broker, while a mainstream mortgage adviser might concentrate on conventional term products.
That division, the panel heard, risks overlooking borrowers who could qualify for several alternatives, including capital-and-interest mortgages, term interest-only borrowing, retirement interest-only mortgages and equity release.
ADVICE SILOS UNDER SCRUTINY
The debate suggested the terminology issue is closely linked to a wider division between mainstream mortgage advice and specialist later life or equity release advice.
One audience member suggested that “later life lending” may itself have developed partly as the industry sought to distance newer products from the historic reputation of equity release.
Several speakers argued that advisers need to be able to recognise a wider range of potential solutions rather than treating age as the point at which a client should automatically be passed into a separate specialist channel.
Diamond said: “Traditionally they would look at it as an age trigger. I can’t do it in mainstream, I’ll pass it to an equity release adviser. But there are so many products in between before you get to that stage.”
Charman said greater adviser education would be required as the market evolved, including consideration of mortgage qualifications, continuing professional development and what the regulator’s interest in more holistic advice could mean in practice.
The discussion ultimately pointed towards a market in which the borrower’s circumstances, income and objectives carry more weight than an age-based label.
Rather than deciding first whether somebody belongs in the “mainstream”, “later life” or “equity release” market, the challenge for lenders and advisers will be to establish the need first and then find the most suitable route to meet it, the panel decided.


