

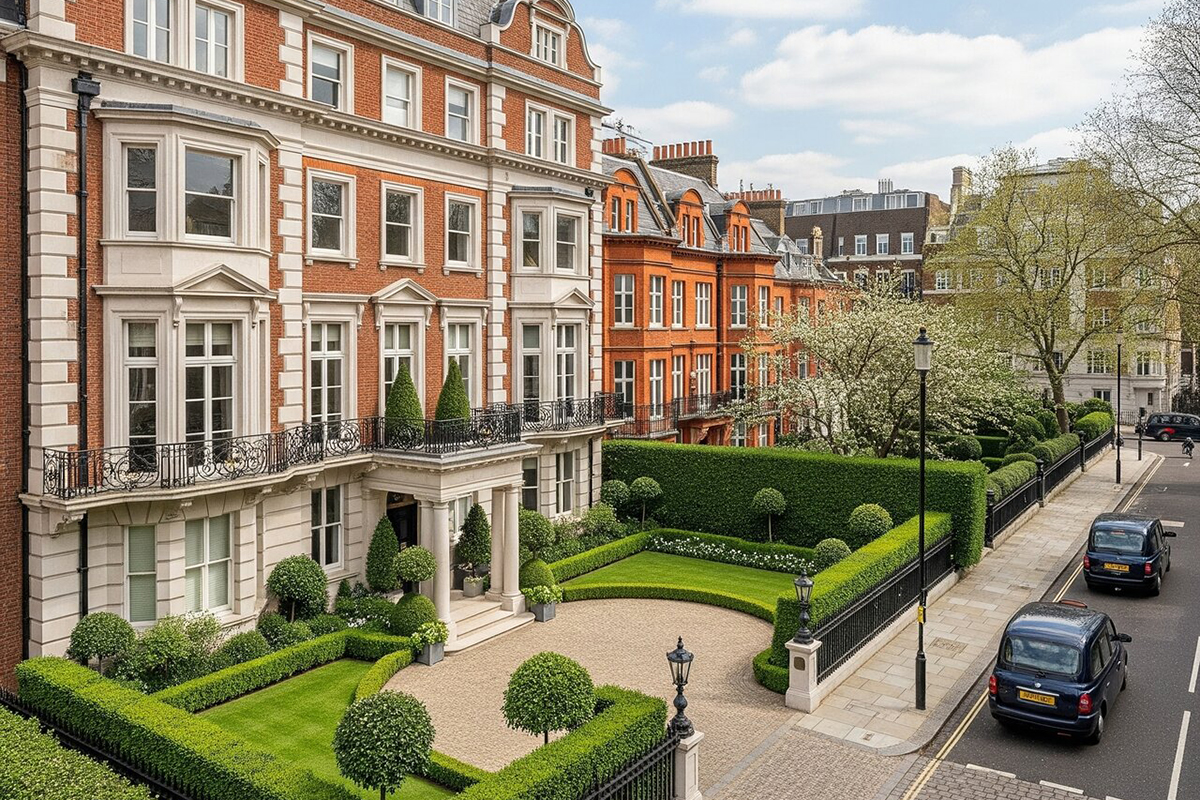
Falling values at the top of the housing market could give some established homeowners a better opportunity to move up the property ladder, according to Moving Compared.
The home-moving comparison service believes softer prime property prices, combined with reports of wealthy residents leaving Britain, could improve the negotiating position of buyers who have previously struggled with the financial jump to their next home.
The argument comes amid further evidence of weakness in the upper reaches of the London market. Cluttons reported that average prime London property values fell 3.1% in the year to June 2026, while prime central London values declined by 4.9%.
Although properties in these markets remain far removed from the price of the typical UK home, Moving Compared said lower values could have consequences further down the property ladder if sellers become more willing to accept offers below previous expectations.
This could particularly benefit homeowners with substantial equity and sufficient income to move, but who have found the difference between their existing property and the larger home, preferred location or more expensive postcode they want to move to prohibitively large.
PRESSURE AT THE TOP OF THE MARKET
The issue has attracted further attention following reports that billionaire hedge fund manager Chris Rokos plans to relocate to Greece after paying £330 million in UK tax last year.
Greece operates a regime under which qualifying wealthy foreign residents can pay a flat annual tax of €100,000 on overseas income. However, Rokos has not publicly confirmed his reasons for moving and the extent to which wealthy residents are leaving Britain remains disputed.
For the housing market, the more significant question is whether such departures translate into additional properties being offered for sale.
If internationally mobile owners decide to dispose of UK homes at a time when demand for expensive property is subdued, buyers immediately below the prime market could find themselves with greater bargaining power.
Rather than requiring homeowners to increase their borrowing or commit more equity, a fall in the price of the property they are targeting could reduce the size of the step between successive rungs of the ladder.
Moving Compared said buyers considering properties that have recently become more affordable should still establish the full cost of a transaction. Early conveyancing and a detailed survey could identify legal, structural or repair issues that might undermine the apparent saving offered by a lower purchase price.
IMPACT COULD FILTER DOWN THE LADDER
Greater movement among established homeowners could also increase the supply of properties available to buyers further down the market. Meanwhile, sellers who are moving overseas rather than buying another UK property may have the advantage of being able to offer a transaction without an onward purchase.
However, leaving Britain does not necessarily remove a seller’s UK property tax responsibilities. Tax residence is determined separately, while non-residents can remain liable for UK Capital Gains Tax when disposing of British property.
The extent of any wider effect will therefore depend less on the number of wealthy individuals announcing plans to leave Britain than on how many subsequently put their UK properties up for sale.
If supply increases while demand for prime homes remains weak, downward pressure on prices could spread into adjacent parts of the market. That, in turn, could make some previously unaffordable moves viable for homeowners who have accumulated equity but have been unable to bridge the gap to their next property.


