

Pepper Money ups second charge max age for earned income

Published on

Pepper Money has increased the maximum age it will accept earned income to and the maximum age at end of term on its second charge mortgages.

Borrowers can schedule their repayments over terms which exceed the state retirement age where they can evidence their income is sustainable.

The lender now accepts across all its second charge products earned income to 75 years of age and a maximum age at end of term of 80.

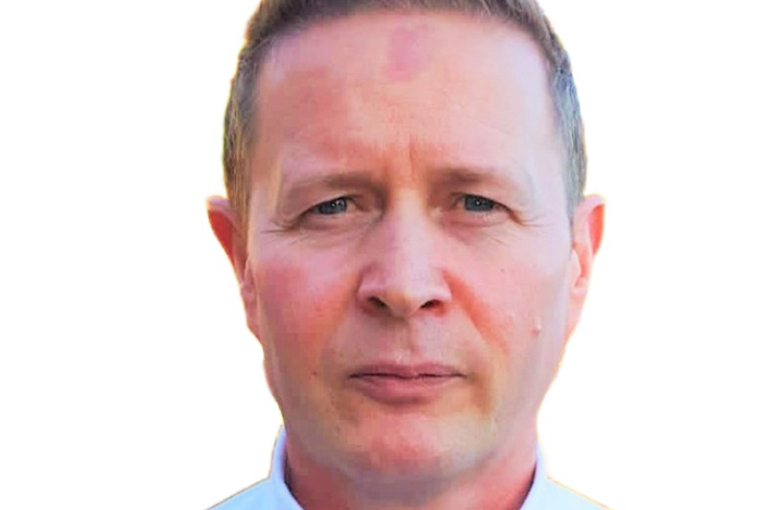
Ryan McGrath (pictured), second charge sales director at Pepper Money, said: “We’re always looking for ways to make our market-leading range of second charge mortgages available to a wider range of customers.

“We recognise that a growing number of customers are likely to be working to an older age. By increasing the age we’ll accept earned income we’re enabling customers to schedule their loan repayments over a term that suits their circumstances. Furthermore, increasing our maximum age at the end of term will enable more customers with retirement income to satisfy their borrowing needs.”


COMMENT ON MORTGAGE SOUP

We want to hear from you!
Leave a comment and get the conversation started.
You need to register to post, so please login or sign up below.

Latest articles

Lifetime ISAs linked to £67.5bn of first-time buyer property purchases

Lifetime ISAs have helped more than 417,000 people buy their first home since the...

Landbay webinar to examine outlook for rates and UK economy

Landbay is to host an economic webinar examining the outlook for interest rates, inflation...

Cost of living hits homeownership plans for more than half of young Scots

More than half of younger adults in Scotland say cost-of-living pressures are the biggest...

Precise cuts residential mortgage offer times with new platform

Precise has launched a residential mortgage platform after a pilot reduced average application-to-offer times...

Impaired credit mortgage sales rise to highest level since 2008

Mortgage lending to borrowers with impaired credit histories has climbed to levels not seen...

Latest publication

Other news

Lifetime ISAs linked to £67.5bn of first-time buyer property purchases

Lifetime ISAs have helped more than 417,000 people buy their first home since the...

Landbay webinar to examine outlook for rates and UK economy

Landbay is to host an economic webinar examining the outlook for interest rates, inflation...

Cost of living hits homeownership plans for more than half of young Scots

More than half of younger adults in Scotland say cost-of-living pressures are the biggest...
