

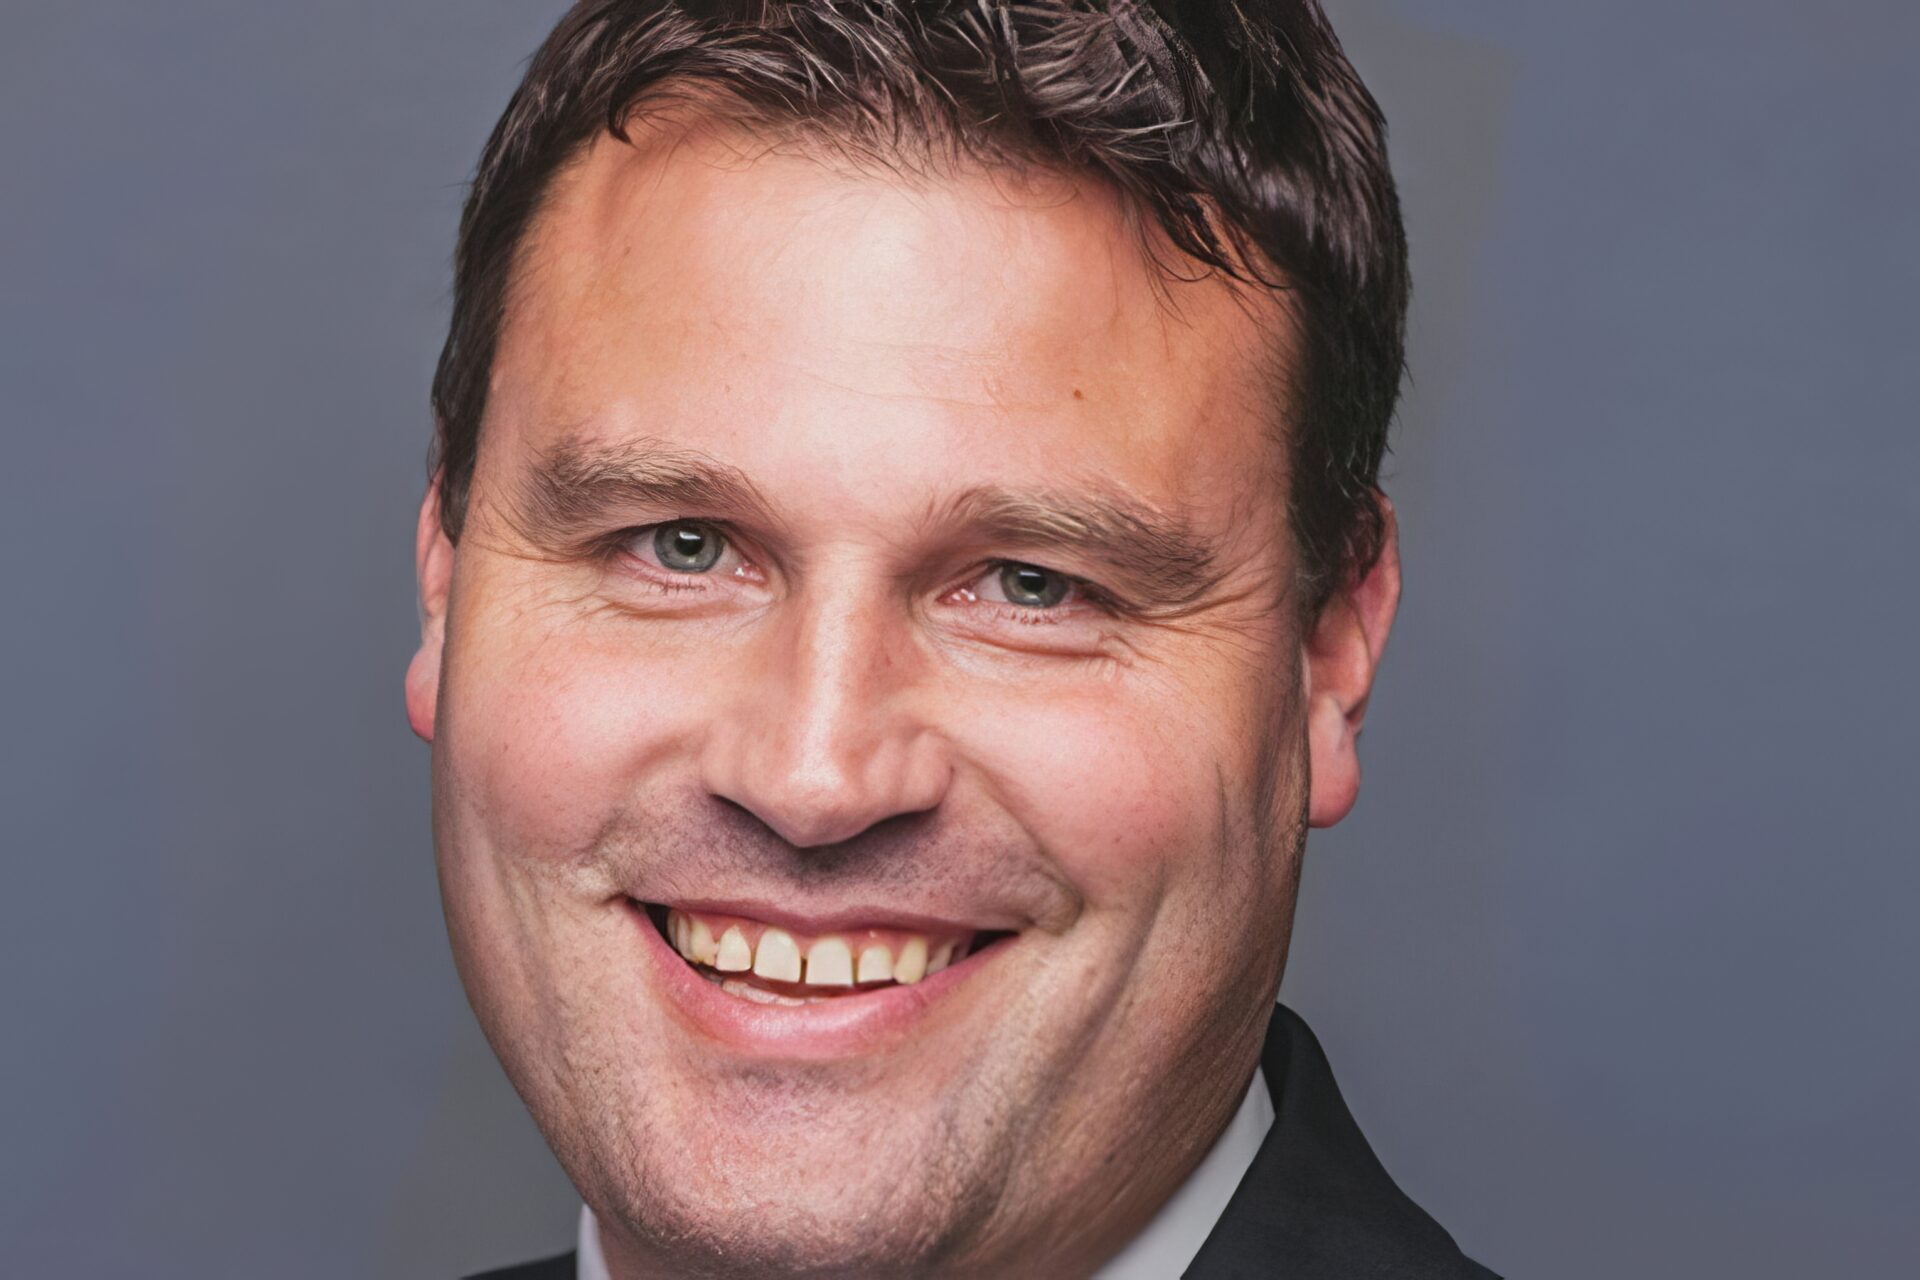
Will Hale, chief executive of Key Advice & Air, has urged the mortgage industry to bring later life lending into the mainstream, arguing that consumer need is already pressing and should not wait for further regulatory change.
His comments follow a wide-ranging speech by FCA chief executive Nikhil Rathi, who last week told delegates at the L&G Mortgage Club’s 30th Anniversary Conference that the regulator’s Mortgage Rule Review would look beyond incremental updates and help shape the “mortgage market of the future”.
Rathi said reform was required to address widening affordability gaps, demographic shifts and the growing number of consumers underserved by traditional lending models.
RETIREMENT PLANNING
Hale (pictured) said Rathi was right to highlight the role of housing wealth in retirement planning, noting that the UK’s £9 trillion of property assets could be used more effectively to support living standards in later life. He called for mortgage advisers and wealth professionals to give far greater attention to the borrowing needs of older homeowners.
He said: “Nikhil Rathi’s speech highlights the importance of later life lending as part of building the mortgage market of tomorrow but the customer need is already evident and this should now be a major focus for advisers in general and mortgage market advisers in particular.”
Hale argued that the government’s own guidance framework should reflect this, saying: “Key would like to see consideration of property wealth included as standard in government-backed guidance services such as Pension Wise and Money Helper. Furthermore, the approach to signposting all options for borrowers over the age of 55 should be applied consistently by lenders and intermediaries.”
He said that despite improvements in product design and consumer safeguards, awareness of later life lending remained limited among both customers and advisers. He pointed to the evolution of lifetime mortgage products, which now include voluntary repayment features and discounts for borrowers who commit to servicing interest, helping mitigate the long-term effects of compound interest.

“More recognition is required around the innovation that has taken place in the later life lending sector and broader acknowledgement that products have moved far beyond just supporting a ‘last resort’ and should be a norm for the many,” he said.
Hale warned that fragmented advice structures continue to restrict access to appropriate solutions. “Across pensions, investments, and mortgages advice is often siloed. Even mortgage advice is split between mainstream and equity release specialists.
“That lack of holistic mortgage advice is holding back customers from being able to access suitable lending options and putting them at risk of opting for solutions which are driven by the type of adviser they consult rather than the ones that will deliver the most suitable outcome.”
He added that good practice already exists in parts of the market, including firms that offer full-spectrum advice and those that operate trusted referral models between mainstream and equity release specialists.
“The options are available for older customers and the direction of travel from the FCA is clear,” Hale said. “There is no need for advisers to wait for the regulator to consult further before taking action.
“Advisers must expand their field of vision and consider all options in order to deliver good outcomes in line with Consumer Duty obligations.”
Hale’s intervention underscores the growing significance of later life lending within the FCA’s broader ambition to modernise homebuying, improve access to finance and ensure housing wealth is better integrated into long-term financial planning.
With the regulator signalling an appetite for system-wide reform, advisers and lenders may face increasing expectations to broaden the advice they offer and adapt to a market in which borrowing in later life becomes both more common and more central to retirement strategy.




