

Gatehouse Bank is making its range of buy-to-let products available to first-time buyers as well as first-time landlords.
The bank has also widened its eligibility criteria for both buy-to-let and Home Purchase Plan (HPP) customers.
The changes mean UK contractors, in particular, will be more likely to be approved for buy-to-let products. Contractors have historically found it difficult to access buy-to-let products because of the demanding affordability criteria and ‘stress tests’ carried out by providers.
However, Gatehouse has further developed its manual underwriting processes to improve access for contractors on a case-by-case basis by taking their full employment income into account.
The criteria for expat and international contractors has also been improved.
In addition, the bank has reduced the minimum property value for Houses in Multiple Occupation (HMOs) and Multi-Unit Freehold Blocks (MUFBs) for UK Residents from £75,000 to £55,000.
The maximum term for buy-to-let products for UK expats and international residents has also been increased from 15 years to 25 years on a rent-only basis.
Home Purchase Plans (HPP) are Shariah-compliant alternatives to traditional mortgages which carry no early payment charges.
Gatehouse has improved the eligibility criteria for its HPP customers so 100% of workers’ guaranteed bonuses, overtime and housing allowance are now taken into account. The income evidence for people on fixed-term contracts and temporary workers has also been changed, making it easier for them to access HPPs.
The minimum property value for UK expats using HPPs has also decreased from £100,000 to £95,000.
The bank will now consider applications from UK nationals, resident in the UK, with only six months continuous employment in the UK, down from 12 months.
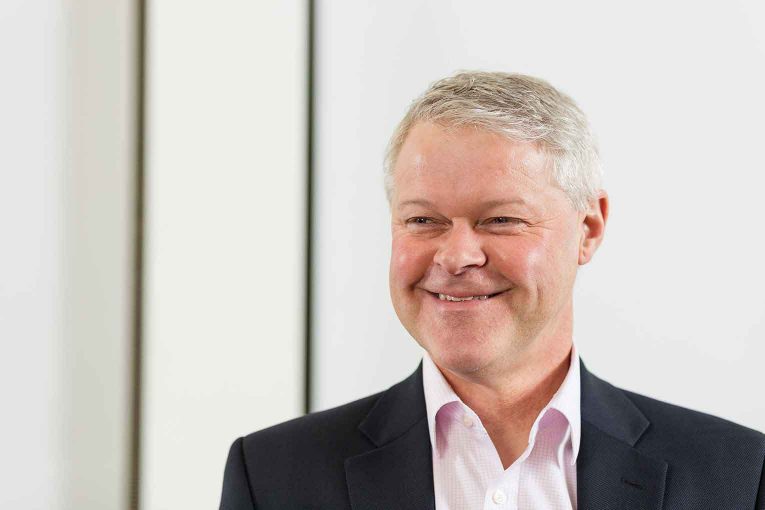
Charles Haresnape (pictured), CEO of Gatehouse Bank, said: “We are continually reviewing every aspect of our buy-to-let and Home Purchase Plan ranges, from the rates through to the small print.
“We will continue to expand the audience for our products and endeavour to better serve those customers who find it difficult to access finance elsewhere.
“Our human approach coupled with smart technology allows us to individually assess applications meaning we can take all our customers’ finances into account, and no one is turned away just because the computer says no.”


