

Suffolk Building Society has returned to the 95% loan to value (LTV) market with residential fixed and discount products.
These three products offer new options for borrowers, including first-time buyers. They include five-year fixed, two-year fixed and two-year discount deals.
The Society has also made reductions on its residential products at 90% and 80% LTV, with up to 29bps off interest-only deals.
The following will be available from Tuesday 11 June 2024:
Residential (C&I)
- 95% LTV two-year fixed at 5.89% until 30 September 2026.
- 95% LTV five-year fixed at 5.49% for 60 months.
- 95% LTV two-year discount at 5.85% for 24 months.
- 90% LTV two-year fixed has been reduced by 4bps to 5.55% (previously 5.59%) until 30 September 2026.
- 80% LTV two-year discount reduced by 14bps to 5.25% (previously 5.39%) for 24 months.
- 80% LTV two-year fixed cut by 10bps to 5.29% (from 5.39%) until 30 September 2026.
- 80% LTV two-year fixed large loan reduced by 10bps to 5.29% (from 5.39%) until 30 September 2026.
Residential (interest only)
- 80% LTV two-year discount interest only cut by 29bps to 5.50% (from 5.79%) for 24 months.
- 80% LTV two-year fixed interest only cut by 25bps to 5.44% (previously 5.69%) until 30 September 2026.
- 80% LTV five-year fixed interest only reduced by 10bps to 5.29% (from 5.39%) for 60 months.
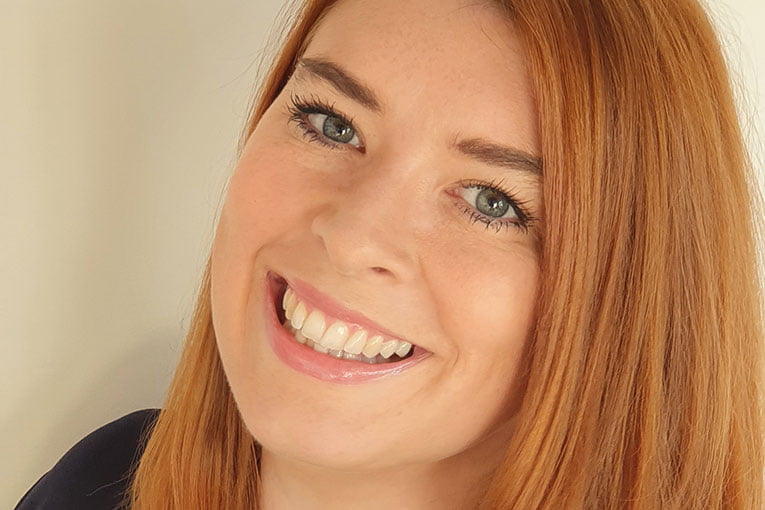
Charlotte Grimshaw (pictured), head of intermediary relations and mortgage sales at Suffolk Building Society, said: “We’re still in a highly dynamic mortgage market. By dropping rates on residential options, and bringing back 95% LTV products for lower-deposit borrowers, we’re helping to put home ownership within the grasp of first-time buyers and keep the cost of monthly mortgage payments down.
“The Society is also pleased to be able to reduce the rates on three interest only products. We know these will help brokers with their later life customers, where we’ve carved out a strong niche, in part due to no maximum age limits and our acceptance of pension assets. Borrowers with larger loans may face affordability challenges, and interest only deals might appeal to them.
“While we’re known for our niches – later life, holiday let, self build, and expat – we write a lot of standard residential business. Our team of manual underwriters assesses each case individually, so one late mobile phone direct debit won’t necessarily trigger the computer to say no.”


