

Oblix Capital has backed calls to improve industry standards and transparency, ahead of the potential regulation of commercial short-term lending.
Following a Treasury Committee in July, in which it was stated that “the justification for leaving commercial lending outside the regulatory perimeter is feeble,” speculation has grown that the FCA will extend its regulation of the bridging sector to include investment and business finance.
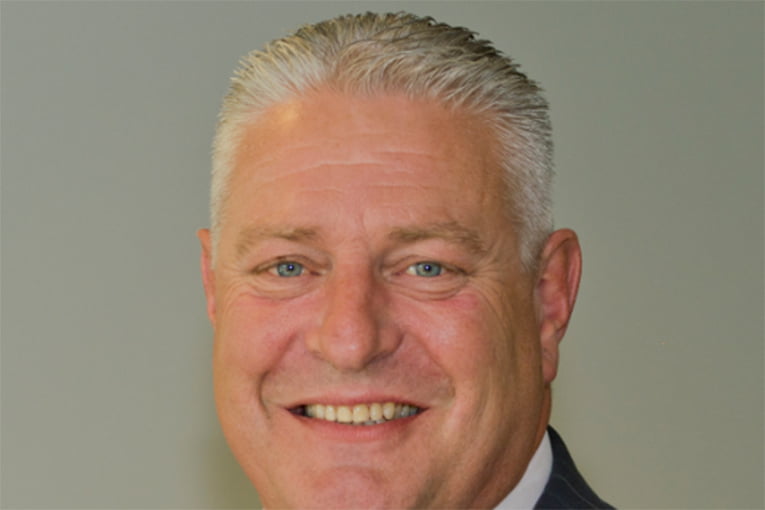
Andy Reid (pictured), sales director at Oblix Capital, said: “There are arguments both for and against the regulation of commercial bridging. The current situation can be confusing for consumers who may not understand how the purpose of a loan can impact their regulatory protection, and regulation across the whole market will help to create a level playing field and more simple choices.
“However, at the same time, full regulation would be likely to increase costs for lenders and brokers. These additional costs could ultimately be passed onto the customer in the form of higher interest rates and/or fees, or could stifle product innovation. Additionally, while some brokers who currently deal exclusively in unregulated loans will change their business model should the market become fully regulated, others could choose to leave the industry altogether.
“However, at the same time, full regulation would be likely to increase costs for lenders and brokers. These additional costs could ultimately be passed onto the customer in the form of higher interest rates and/or fees, or could stifle product innovation. Additionally, while some brokers who currently deal exclusively in unregulated loans will change their business model should the market become fully regulated, others could choose to leave the industry altogether.
“Whatever happens in the future, we think the industry should continue to push to raise standards and transparency now. If we are able to demonstrate a collective commitment to high standards, regulation is likely to have a less disruptive impact on our practices if and when it is introduced.
“At Oblix Capital, for example, we adhere to the ASTL’s Code of Conduct that requires fairness, transparency and high standards of underwriting – and we believe that this is the type of approach that all lenders should take now, whether an ASTL member or not, to help protect the future of our market.
“Similarly, brokers have a role to play in choosing to work with lenders that demonstrate this sort of commitment to quality, as this will encourage other lenders to raise their game. Only by collectively committing to better standards will we be able to ensure a strong position ahead of any potential regulation in the future.”


