

Nottingham Building Society has announced the latest in a series of mortgage criteria changes designed to streamline the mortgage process for both brokers and customers.
The Society has also revised its maximum loan sizes, enabling more customers to access suitable mortgages for their dream homes.
The revised maximum loan sizes based on loan-to-value (LTV) ratios are as follows:
- LTVs ≤ 75%: Up to £1.5 million
- LTVs ≤ 80%: Up to £1 million
- LTVs ≤ 90%: Up to £750,000
- LTVs ≤ 95%: Up to £500,000
This applies to all residential mortgages except RIO, self-build and new builds which have the following maximum loan sizes: RIO £500,000, self-build £600,000 and new build £750,000. These increased loan limits will open up new opportunities for customers to secure the financing they need in their pursuit of home ownership.
To further streamline the mortgage application process, the Nottingham has also eliminated the need for bank statements in the majority of cases where the LTV is 80% or below. Brokers will no longer be required to upload bank statements into the portal. In some cases however, underwriters may still request bank statements if necessary to support the lending decision.
The Nottingham will now accept mortgage applications from individuals currently in a probationary period, subject to underwriter discretion. These changes will mean that more customers can confidently apply for a mortgage with Nottingham Building Society.

In addition, the Nottingham will help to streamline the process for self-employed mortgage applicants. Previously, the Nottingham required the submission of three years’ worth of accounts, but this has now been reduced to two years of accounts or an SA302 form, dated in accordance with HMRC requirements.
The Nottingham has also broadened its list of recognised organisations and qualifications for accountants.
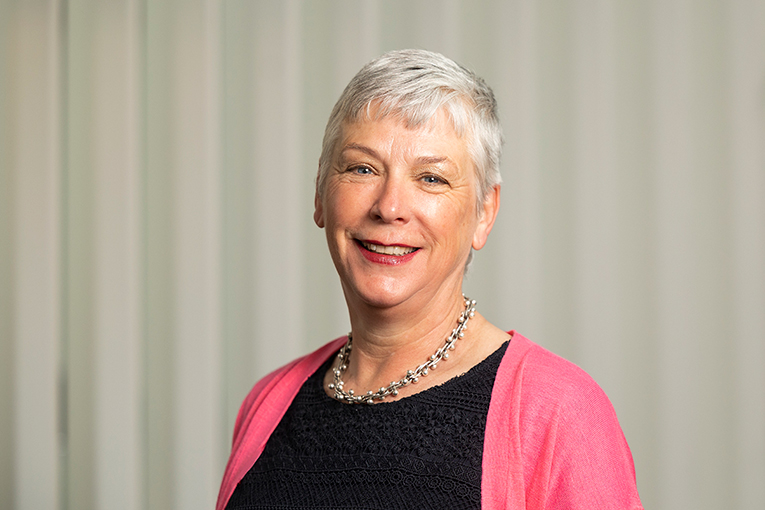
Alison Pallett (pictured), Nottingham Building Society sales director, said: “We’re excited to be able to adapt our criteria as we strive to help our members in their pursuit of home ownership, and further support brokers as they work with us.
“As the economic climate remains unsteady and the impact of that is felt across the housing market, brokers will become even more important to borrowers looking to navigate this environment and find the best deal. This is why we want to ensure that we are always looking at ways to ensure that we are streamlining our processes.
“What’s more, the realm of employment is undergoing a transformation, with an increasing number of individuals falling into self-employed classifications. It is therefore crucial for the industry to respond accordingly. Our new criteria will allow more self-employed workers to access mortgage financing more easily.”




