

Mortgage lenders need to keep adapting their criteria as changing working patterns leave growing numbers of prospective homeowners with incomes that no longer fit traditional employment models.
One in five Scottish adults now has a complex income, including people who are self-employed, contractors or earn money through multiple or irregular sources, according to research discussed during the latest Knowledge Bank Lenders Live.
Among Scottish non-homeowners with complex incomes, 55% fear they may never own a property, compared with 47% of non-homeowners overall.
Yet demand remains, with 11% of self-employed adults in Scotland intending to buy a home during the next year.
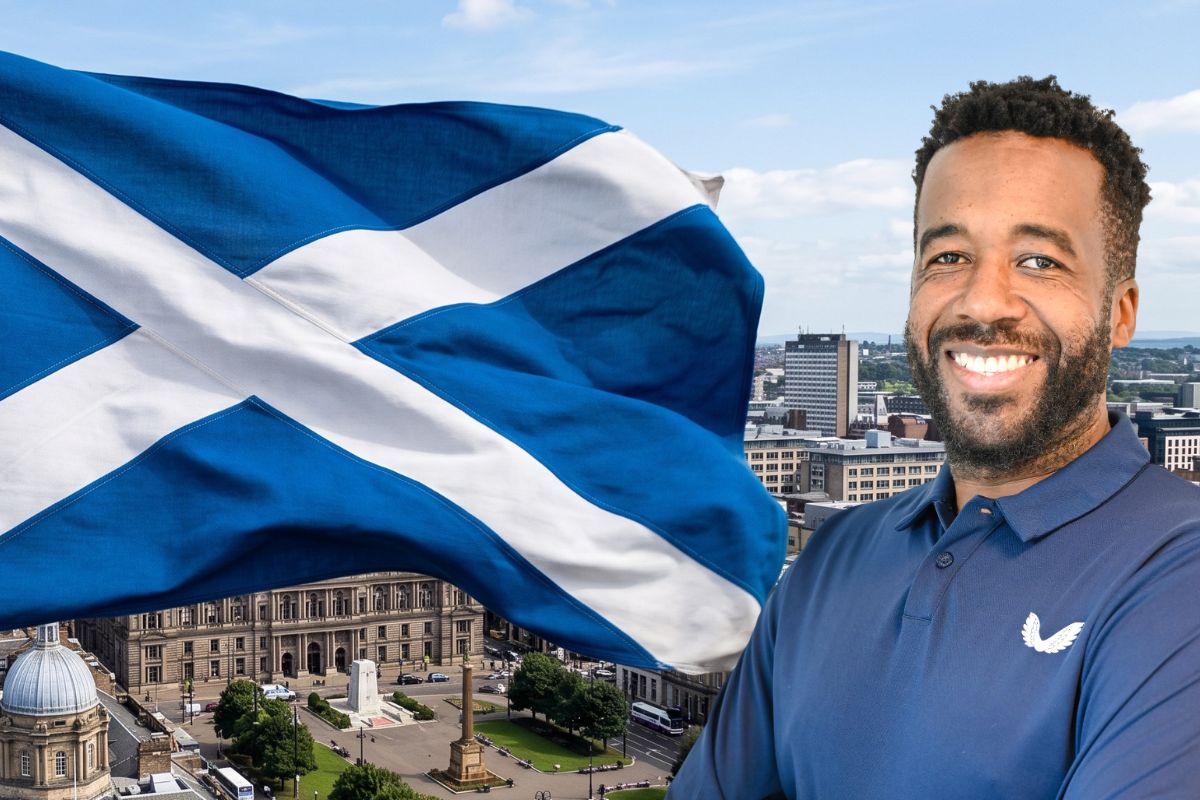
The 192nd Lenders Live brought together Jason Wilde, head of sales at Paragon Bank; Joel Bailey-Wilson, founder and mortgage and protection adviser at Meta Mortgages; Gabrielle Latifi, senior regional account manager at Landbay and Claire Askham, head of sales at Buckinghamshire Building Society. The session was hosted by Knowledge Bank sales director Shane Chawatama (main picture, inset).
WHEN ‘COMPLEX’ BECOMES NORMAL
A Lenders Live audience poll found 43% believed complex-income borrowers were definitely still unfairly disadvantaged by mortgage criteria, with another 43% saying this remained the case with some lenders.
Just 14% believed applicants with complex incomes were now much less disadvantaged than previously.
Wilde said complex incomes were not unique to Scotland but reflected a much wider change in employment and working patterns.
“A lot of the generation coming through will be working in the gig economy, so their incomes may be coming from several different places,” he said. “That is potentially a much bigger issue that is brewing across the market.”
The panel also considered why some lenders remained hesitant about entering Scotland.
While the underlying mortgage assessment may be similar, Scotland’s different legal and property system can require lenders to adapt back-office processes, technology and solicitor panels, alongside having people with the necessary local expertise.
Wilde said having a genuine presence in Scotland was important.
“You need boots on the ground,” he explained. “Having a BDM or wider presence there makes a real difference. Scottish brokers can sometimes feel that industry conversations focus heavily on England and Wales and leave them out.”
He added that lenders needed to weigh the cost of adapting their operations against the potential size of the market, but said Paragon’s experience demonstrated Scotland could provide good-quality, sustainable business supported by knowledgeable brokers and landlords.
IS ‘COMPLEX’ THE WRONG LABEL?
Askham agreed that complex income was increasingly a feature of the wider mortgage market rather than a specifically Scottish issue.
Applicants can combine employment with self-employment, contract work, income through an umbrella company, benefits or pensions.
As a result, the underwriting question is increasingly about the sustainability and stability of that income rather than whether it conforms to a conventional employment model.
The panel also questioned whether the term “complex” was being applied too readily.
A self-employed applicant or contractor may appear complicated to someone unfamiliar with that area of the market despite established mortgage options being available.
Bailey-Wilson said: “What one person considers complex may not be complex to someone who regularly handles those cases.
“There is more work to be done around understanding the options, the flexibility lenders can offer and the different ways people now receive their income.”
He also stressed the importance of prospective borrowers speaking to a broker before making significant career or financial decisions.
Customers can concentrate on building a deposit only to discover later that their income structure, accounts, affordability or existing credit commitments affect their mortgage options.
“If you are thinking about getting a mortgage, have that conversation sooner rather than later,” Bailey-Wilson said. “Even if you are not ready to proceed today, understanding what you need to do will put you in a much stronger position.”
Chawatama said: “The way people work has changed, but too many prospective buyers still assume that being self-employed, contracting or having multiple income streams means homeownership is out of reach.
“There are lenders that understand these circumstances, but brokers need clear, current criteria to identify them. Lenders also need to listen closely to what advisers are seeing so their criteria continue to reflect the customers coming through the door today.”
BUY-TO-LET AT 30
The session also looked at the evolution of buy-to-let as the market marks its 30th anniversary.
The landlord profile has changed substantially during that time, with professional and portfolio-focused investors becoming more prominent and limited company ownership increasingly common among new purchases.
Wilde said landlords had repeatedly demonstrated their ability to adapt to tax, regulatory and economic changes.
“Anyone entering the market today is generally looking carefully at yield and is increasingly purchasing through a limited company,” he said. “That is completely different from even ten years ago. The market has adapted and will continue to adapt.”
The panel argued that the private rented sector continued to play an important role because the UK did not have enough homes to meet demand across owner-occupation, social housing and private renting.
Asked what UK housing needed most, 67% of the Lenders Live audience selected more owner-occupied homes, although the panel stressed that increasing homeownership would not remove the need for good-quality rental accommodation.
DIGITAL HOME-MOVING REFORM
The panel also called for the mortgage industry to engage earlier with plans to modernise the home-moving process through digital property data, material information and digital sales packs.
Government smart-data schemes are expected to become operational in 2030, but better sharing of property information before then could reduce duplication and shorten transactions while cutting the amount of chasing between estate agents, brokers, lenders, surveyors and conveyancers.
Latifi said buyers would benefit from having more information before committing significant time and money to a property.
“If we knew more information upfront, it would be massive,” she said. “It would remove some of the uncertainty for buyers who are already thinking about their income, deposit and whether they can obtain the mortgage.”
Askham supported the principle but said implementation would require different parts of the property market to work consistently.
Some lenders and firms would be able to adapt their technology more quickly than others, while smaller organisations could face greater costs and challenges from legacy systems.
The panel concluded that digital reform could materially improve the customer journey, but would require lenders, brokers, estate agents, conveyancers and technology providers to help shape the process together.
Chawatama added: “Whether the issue is complex income, landlord finance or the home-moving process itself, the common theme is that the market must reflect how people live and work today.
“Innovation will only achieve its full value if it is supported by accurate information, clear criteria and collaboration across the entire property journey.”
Lenders Live is hosted by Knowledge Bank and brings together brokers, lenders and other mortgage professionals to discuss the issues and trends shaping the industry.
Register for the next episode taking place on October 5 HERE.


