

The Ipswich Building Society has re-entered the shared ownership mortgage market with new fixed rate deals.
The products are two and five-year fixed rate deals for up to 95% LTV of the borrower’s share and a two-year fixed rate mortgage of up to 90% LTV of the borrower’s share.
The following products are all available for purchase and remortgage cases, each with no application, completion or valuation fees. A minimum loan of £75,000 and maximum £500,000 applies:
Up to 95% LTV of the share being purchased:
- Two-year fixed rate at 3.74% until 30 November 2023, then reverting to SVR (currently 5.24%) minus 1.74% until 28 February 2027
- Five-year fixed rate at 3.99%, fixed for 60 months from the date of completion
Up to 90% LTV of the share being purchased:
- Two-year fixed rate at 3.25% until 30 November 2023, then reverting to SVR (currently 5.24%) minus 1.74% until 28 February 2027
All products have a CHAPS fee of £35. During the initial mortgage term, the Society offers fee-free overpayments up to 50% of the original loan amount.
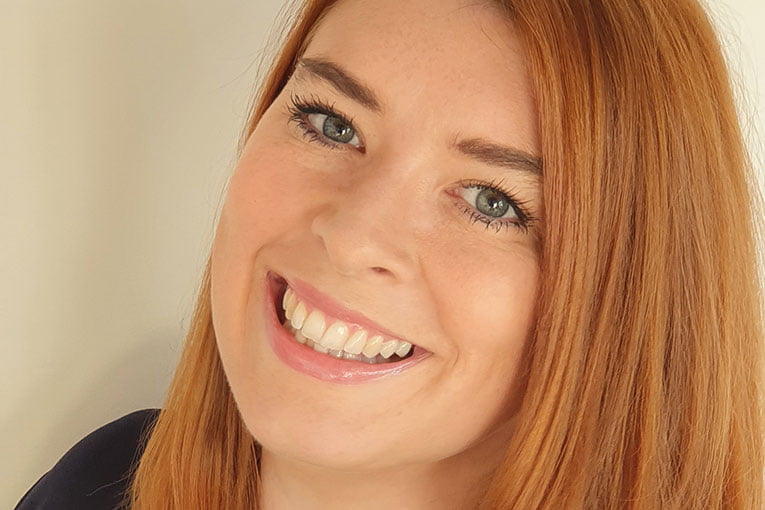
Charlotte Grimshaw (pictured), head of intermediary relations at the Ipswich Building Society, said: “It’s great to be back in the shared ownership market once again. Our previous range was very popular and, having implemented other crucial changes to our products and lending criteria, we have been committed to bringing these products back into our range to make buying a home more accessible.
“With house prices rising faster than wages, and fewer higher LTV deals on the market than before the pandemic, shared ownership mortgages can offer a more affordable, achievable option for would-be borrowers.
“In particular, I’m excited about our five-year fixed rate product, which should provide borrowers with comfort and security over their mortgage repayments, offering stability over a longer time period. Additionally, as the affordability assessment for this five-year fixed rate product is calculated on product pay rate only, rather than applying a stress scenario, this will further help those looking to borrow.
“Recent research shows that nearly two thirds of first time buyers have to rely on an additional source of income when saving for a mortgage deposit. It’s clear this generation is working hard to fund their dreams of owning their own home, and we’re keen to support them. These new products, combined with our personal approach to underwriting, allow us to offer borrowers more choice while retaining a diligent approach to lending.”


