

Pepper Money improves second charge criteria

Published on

Pepper Money has introduced enhanced lending criteria for self-employed second charge mortgage customers.

The lender says it is looking to level the playing field with its changes, as 80% of self-employed people say that self-employment makes it more difficult for them to secure a mortgage.

Now, self-employed customers now have access to the same rates as employed borrowers up to 95% LTV.

In addition, self-employed applicants can use their latest year’s income for affordability calculations across all products.

For Pepper Money’s Prime and XLTV ranges, the lender will request two years’ proof of income and on its Plus range it will request just one year.

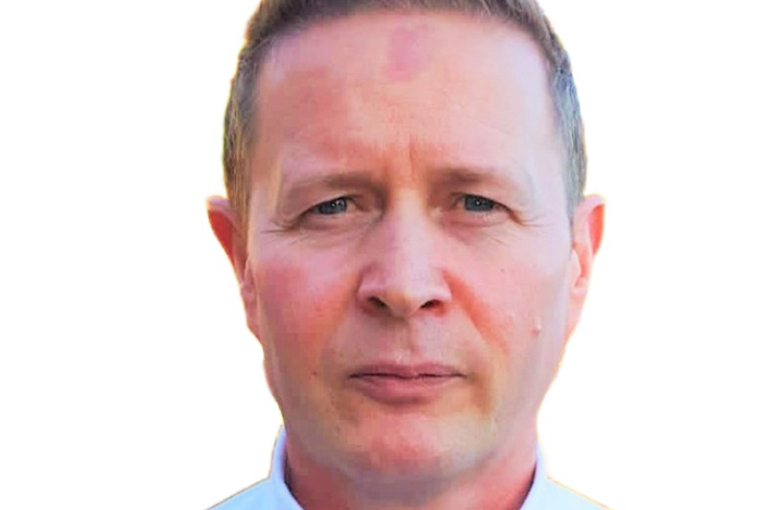
Ryan McGrath (pictured), second charge sales director at Pepper Money, said: “Pepper Money has established a strong reputation in providing lending opportunities that level the playing field for the self-employed, and these improvements will help to enhance that reputation.

“When it comes to second charge mortgages, we have recognised some of the challenges faced by self-employed customers and improved our criteria to address those challenges head-on. As market leaders in the second charge space, we understand that you can never rest on your laurels and these are just the latest in a full programme of ongoing enhancements to our proposition to ensure that we are best placed to help even more customers.”


COMMENT ON MORTGAGE SOUP

We want to hear from you!
Leave a comment and get the conversation started.
You need to register to post, so please login or sign up below.

Latest articles

Cost of living hits homeownership plans for more than half of young Scots

More than half of younger adults in Scotland say cost-of-living pressures are the biggest...

Precise cuts residential mortgage offer times with new platform

Precise has launched a residential mortgage platform after a pilot reduced average application-to-offer times...

Impaired credit mortgage sales rise to highest level since 2008

Mortgage lending to borrowers with impaired credit histories has climbed to levels not seen...

Councils to gain earlier powers over long-term empty homes

Councils will be able to intervene when homes have stood empty for six months...

Phoebus completes latest SOC 2 Type II assessment

Phoebus Software has renewed its SOC 2 Type II attestation after KPMG assessed the...

Latest publication

Other news

Cost of living hits homeownership plans for more than half of young Scots

More than half of younger adults in Scotland say cost-of-living pressures are the biggest...

Precise cuts residential mortgage offer times with new platform

Precise has launched a residential mortgage platform after a pilot reduced average application-to-offer times...

Impaired credit mortgage sales rise to highest level since 2008

Mortgage lending to borrowers with impaired credit histories has climbed to levels not seen...
