

Shawbrook has made major changes to its core commercial mortgage proposition.
The specialist lender has identified increased demand for investment in commercial property over recent months. In response to this demand, the bank says it is enhancing its products to deliver complex funding solutions which better cater to specialised commercial investors and landlords seeking to diversify their portfolios over the coming months.
Some of the key changes Shawbrook has made to its commercial and semi-commercial mortgage products include:
- Reducing the minimum loan size to £250,000
- Reduction of rates across the offering by 10bps
- Increasing the maximum LTV by 5% on semi-commercial products to 75% and commercial products to 65%
- Re-introducing retail assets as acceptable security
- Relaxing experience requirements for applications from buy-to-let landlords.
Shawbrook has revised some elements of criteria to manage increased deal flow in a more volatile market:
- Implementing a minimum EPC rating of ‘C’ for office properties valued over £2m
- Streamlined automated decision making enhanced with referrals to an underwriter on day one for higher LTV deals
- Adjusting loan terms with interest only available for up to 12 years and capital or part-capital repayment loans for up to 25 years all available across our range of 2, 3, 5 and 10-year fixed rates alongside a flexible variable rate option.
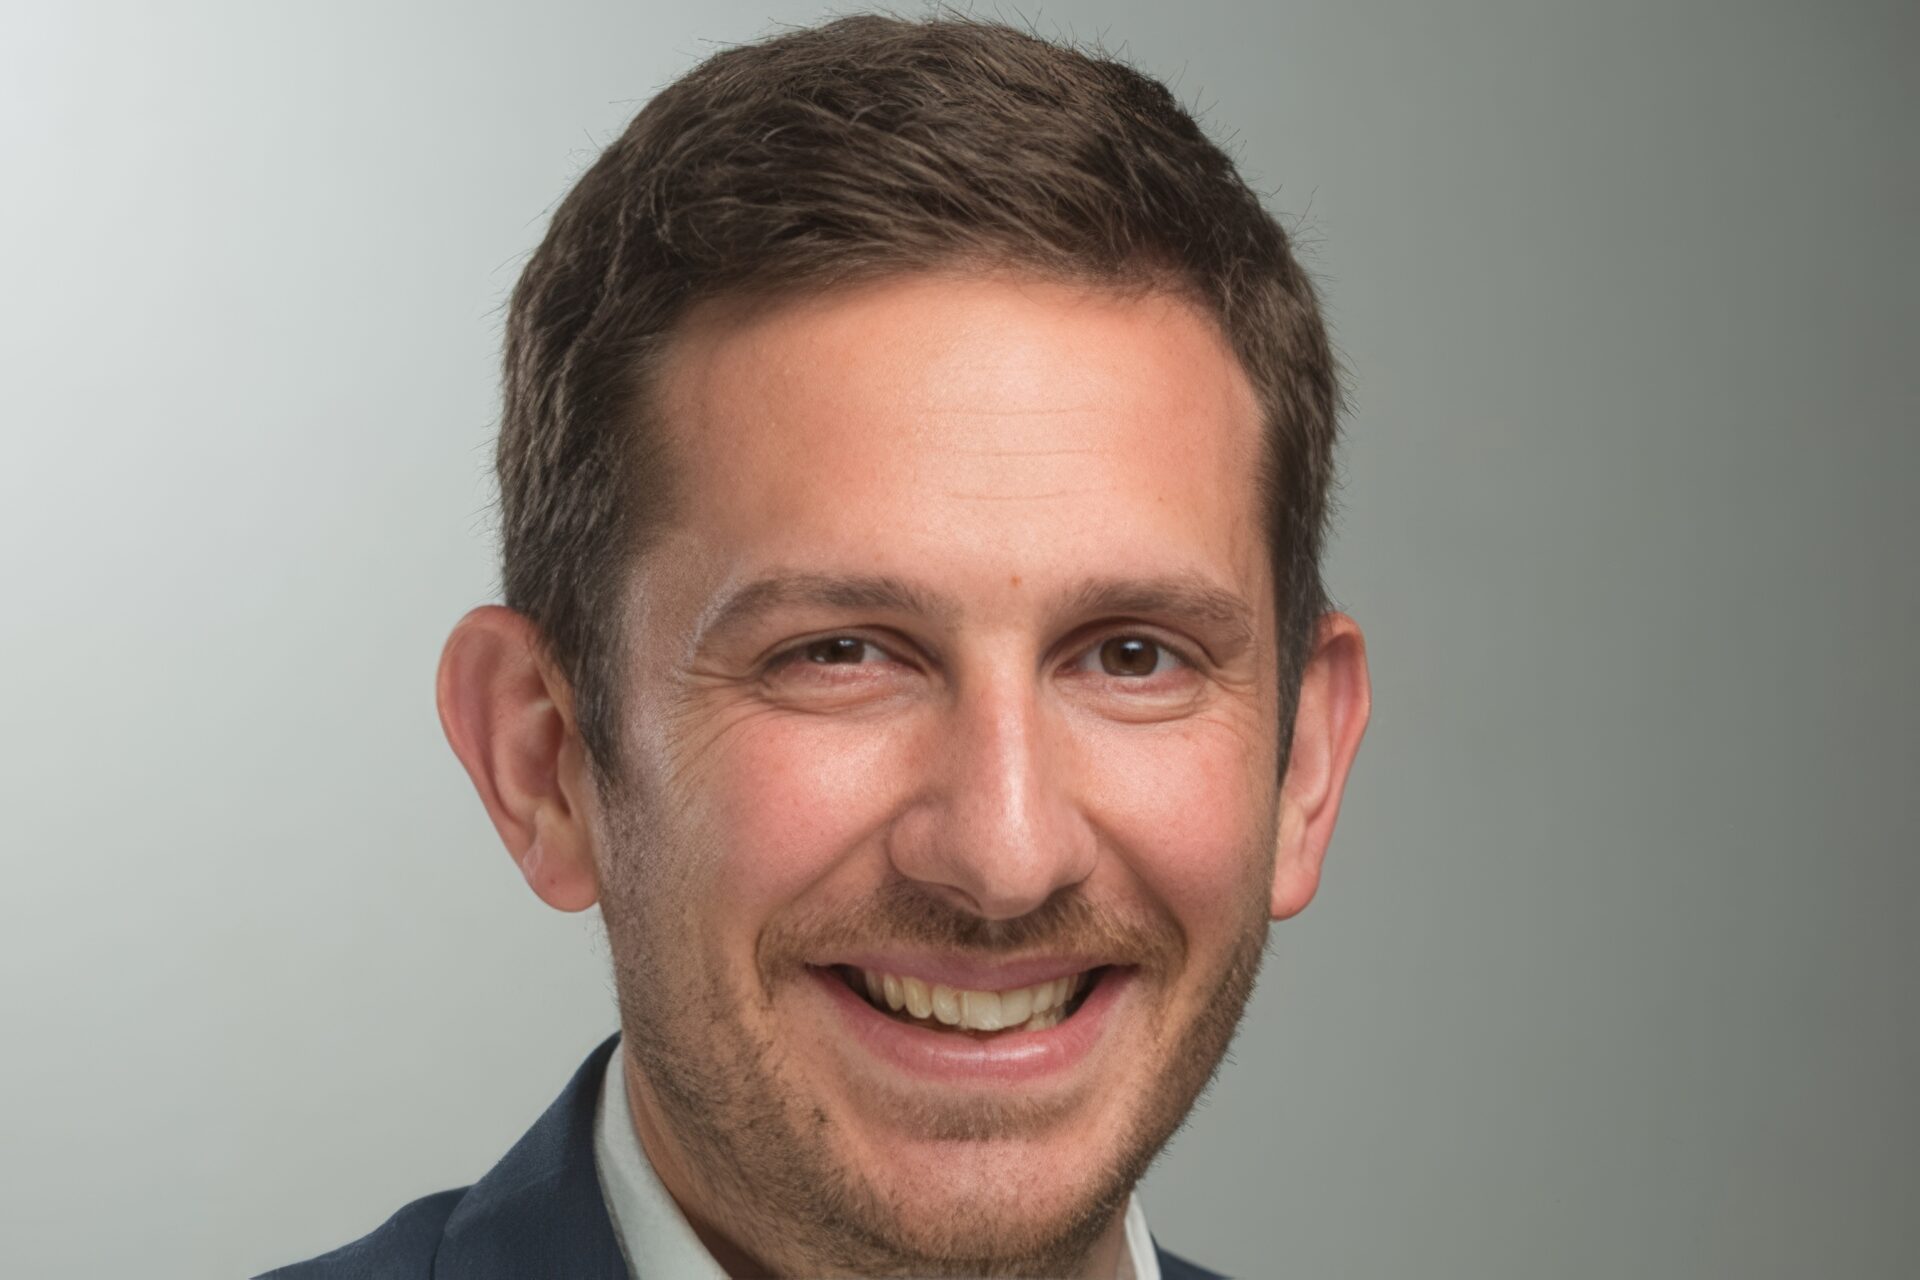
Daryl Norkett (pictured), head of real estate proposition at Shawbrook, said: “Shawbrook is committed to staying at the forefront of the real estate market, and we have been tracking the commercial property market closely. Having monitored the market and our own deal flow over the past few months, we are making changes to respond to growing demand from professional investors and landlords for commercial property.
“Our seasoned team of property specialists, supported by our expert broker partners, enable Shawbrook to adeptly navigate the complexities of a wide range of real estate financing. These latest enhancements helps to extend even more support to property professionals, whether that be a seasoned commercial property investor or a buy-to-let landlord looking to expand. ”





