

The Financial Services Consumer Panel has welcomed the publication of the final rules for the Mortgage Market Review (MMR), but has warned that the regulator will need to supervise the new rules “carefully and consistently” to ensure good outcomes for borrowers.
The Panel argues that the rules will have to be rigorously supervised and enforced in order to be effective.
It considers the introduction of new rules for ‘mortgage prisoners’ to be particularly welcome and has urged the FSA to ensure that it exercises vigilance when monitoring firms’ compliance.
The Panel will also monitor the revisions to the rules around the provision of advice as these develop.
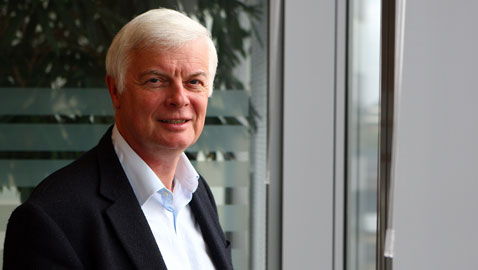
Adam Philips (pictured), Consumer Panel chair, said: “The MMR has been an enormous piece of work for the FSA. The Panel has devoted considerable time to analysing it, commissioning two substantial pieces of research on the FSA’s welfare analysis for example. We note that the FSA has listened to our concerns and ideas in a number of areas, particularly on mortgage prisoners, and is taking action to prevent exploitation and abuse by firms. As we have flagged all along, relying on the principle of treating customers fairly alone is clearly not enough.
“Getting right the balance of consumer interests affected by the MMR has been a central part of the debate. It is vital that vulnerable consumers are protected but in a manner that does not deprive the creditworthy from accessing mortgage finance. We believe these aims would have been more easily achievable had the FSA accepted in full our recommendations regarding mortgage prisoners, the estimation of living costs, interest rate stress testing, and the timing of implementation. An even greater burden will be placed on supervisors and enforcers to adopt a consistent yet flexible approach.
“Supervision and enforcement are, in any case, the keys to the effectiveness of the MMR: weaknesses in these areas materially contributed to regulatory failure during the pre-2008 housing market bubble. This is why the Panel urges vigilance in implementation: a number of the new regulatory rules are very welcome, but it would be unwise to consider that this is yet ‘job done’.”


