

Gatehouse Bank has widened the eligibility criteria on its range of buy-to-let products, including an increase to the maximum age at the end of the term, from 85 to 99 years for UK residents.
The 99-year age limit will not apply to customers who rely on non-rental income to meet affordability criteria. Where there is a reliance on personal income, the maximum age remains 85.
The change to the upper age limit is designed to remove financing challenges for older clients, who would otherwise have no problem passing affordability tests.
Gatehouse will also now allow refinancing within six months of purchase for all buy-to-let customers, subject to an enhanced due diligence process.
Buy-to-let products for expats and international residents have also been amended, with the maximum finance-to-value increasing from 75% to 80%, to bring it in line with products for UK residents.
The minimum finance amount has also been reduced to £60,000, down from £75,000, and the minimum property value reduced from £100,000 to £75,000 for expats and international residents.
The bank will now require three months of bank statements from expats, rather than 12 months, while international residents will only need to provide six months’ worth of statements, rather than 12 months – conditions apply.
The maximum age increase and reduction of statements also apply to Houses in Multiple Occupations (HMOs) and Multi Unit Freehold Blocks (MUFBs).
The bank has also made some changes to its Home Purchase Plan criteria, and refinancing is now allowed within six months of purchase, subject to further due diligence checks. Home Purchase Plans are Shariah-compliant alternatives to conventional mortgages which carry no early payment charges.
The bank last changed its eligibility criteria in October 2019. Its manual underwriting process, ensures all applications are judged on a case-by-case basis, taking the applicant’s full circumstances into account.
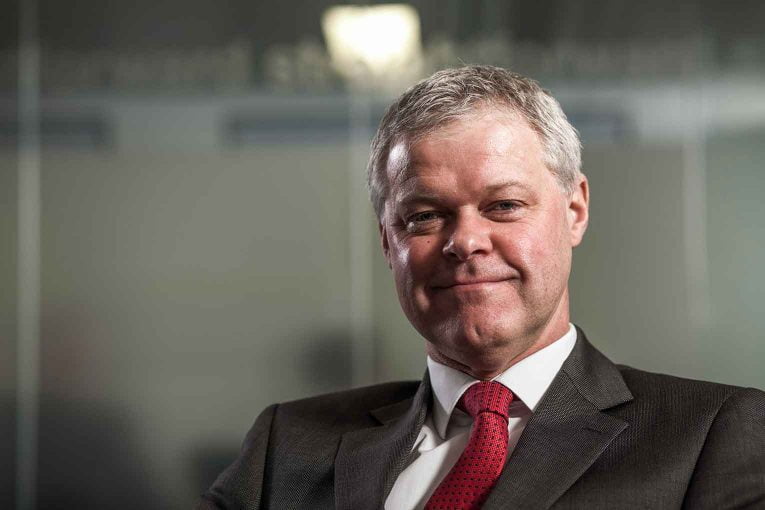
Charles Haresnape (pictured), CEO of Gatehouse Bank, said: “We are always looking at ways to improve our buy-to-let and Home Purchase Plan ranges to ensure we make the application process as easy as possible for our brokers and customers.
“We are able to make the latest changes to our criteria because of our human approach to underwriting, which means we take our customers’ full financial circumstances into account.”


