

The capability of consumers to engage has been identified as the largest area of vulnerability, according to the latest results from the MorganAsh Resilience System (MARS).
Engagement capability includes key factors such as language, digital interaction and coercion. The willingness to engage was the highest reported issue among MARS users. According to MorganAsh, these traits occur in around 12% of consumers.
MARS breaks down vulnerability into three primary characteristics: health, wealth and life events – mirroring the FCA’s own categories. This is followed by three secondary characteristics: financial capability, engagement capability and support network. As might be expected, physical health issues are far more prevalent than mental health issues.
MARS identifies over 400 variations in characteristic and circumstance that can lead to consumer vulnerability.
The findings come as more firms implement vulnerability assessments, to meet the upcoming Consumer Duty regulations.
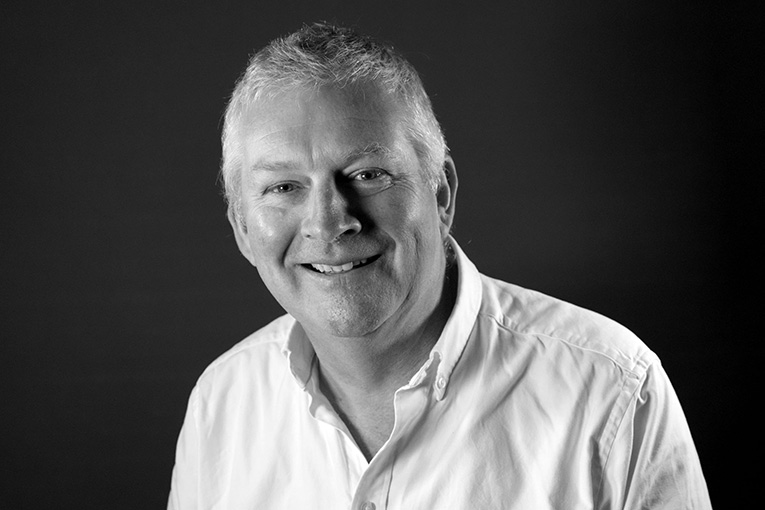
Andrew Gething (pictured), managing director of MorganAsh said: “With firms now starting to receive detailed analysis of consumer characteristics from vulnerability systems, it’s interesting to see users of MARS identifying engagement as a key challenge. Thankfully, amending the client’s communications strategy to overcome engagement issues is a relatively understood issue.
“Understanding the consumer’s ability to engage, and their financial understanding, is already used to guide those who provide advised and non-advised services. The aim is to allow those with good financial knowledge to self-serve, while trying to nudge those who don’t into an advised process.
“At present, firms are reluctant to stop those with poor financial knowledge from transacting on a self-serve non-advised basis – partly to understand the process more, and partly in fear of losing business to competitors. How this plays out once Consumer Duty comes into force will be interesting. We do need more data and to understand this better – and we also need to explore how easy or not to nudge people into advice – and if this is appropriate.
“Consumer Duty should provide a level playing field – so, if consumers switch to a firm with fewer checks, the receiving firm should amend their process. Otherwise, they may find that when the self-policing requirement of Consumer Duty comes into force, others may report them to the FCA. The FCA is already asking firms to pass on such information.”


