

Bridgewater Equity Release has launched the latest in its series of ‘Just a thought…’ aids for advisers to offer their introducers.
The home reversion specialist’s latest aid is entitled ‘The price of long-term care’ and looks at the recent government proposal to cap the amount individuals will pay for their social care at £72,000.
The aid provides a breakdown on the latest proposals and helps introducers understand how this affects individuals, whether they qualify for ongoing State support or not. It focuses on the problems that will still remain for many in funding their own care even with a cap now being placed on the total amount.
The aid also gives a breakdown of the key social care statistics and the likely impact on individuals as they live through their retirement and looks at how they cover the costs of care. It includes statistics on the number of individuals with long-standing illnesses, the number who have care and support needs the State doesn’t support, average weekly fees for those in private residential care and the average length of stay.
In addition, it looks at the potential solution that equity release can provide given that the cap will only cover services which are available at the normal council cost; those who want a higher specification of care home or who want to pay more for extra help will have to fund this themselves.
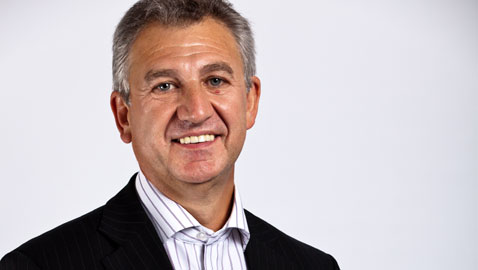
Chris Prior (pictured), manager, sales and distribution at Bridgewater Equity Release, said: “Our ‘Just a thought…’ aids are always designed for advisers to give to their introducers in order to help them understand an issue like the funding of social care, and to highlight where equity release may be able to provide a solution.

“While the cap on social care funding has been broadly welcomed by the industry many individuals in retirement will still have to find significant sums of money, not forgetting the fact that any care above and beyond the council cost will also need to be paid for personally. This is therefore not a case of ‘problem solved’ for large numbers of people but simply an understanding that their contributions will not necessarily go beyond a certain level. That said, many introducers will be dealing with large numbers of clients who will be struggling to identify how they go about finding this amount of money.
“Whilst not the only solution, equity release is in the future likely to be used far more for this type of reason and specialist advisers can hand out this ‘Just a thought…’ in order to educate and inform their introducers of the help they can provide in this area.”




